
Yes, you can buy property in Pakistan from abroad without visiting. Overseas Pakistanis in the UAE, UK, Saudi Arabia, Qatar and the USA do it every month. This guide walks you through the six steps: get your identity documents in order, open a Roshan Digital Account, move the money cleanly, appoint someone to sign for you, choose and complete the purchase, and plan how you will get the money back out when you sell. The hard parts are not the paperwork. They are the small decisions that save or cost you years. We explain each one honestly, with the three Invenza projects best suited to buyers from your country at the end.
| Who this guide is for: NICOP or POC holders living abroad who want to buy property in Pakistan, primary market, resale, or under-construction. If you are a foreign national (non-Pakistani origin) looking to buy, the process is different and this guide does not cover it. |

Before Anything Else: Three Decisions
Most overseas buyers lose money not because they picked the wrong project but because they skipped these three questions. Answer them before you look at a single floor plan.
1. What is the property for?
Monthly income? Capital growth? Somewhere to live in ten years? Each answer leads to a different kind of property. A hotel suite that pays rent is useless if you want a family villa to retire into. A plot in a quiet phase is useless if you need cash flow.
Write the answer in one sentence before you continue.
2. Who will sign for you?
If you cannot be in Pakistan when the paperwork moves, someone else signs on your behalf. That person is your attorney under a Power of Attorney. In Pakistan this is normally a parent, sibling, or spouse already in the country. If you have no family member you trust fully with legal signatures, the whole purchase becomes harder.
We recommend appointing two attorneys who must act jointly. One signature means one person can make a mistake unchallenged. Two acting together is a quiet safeguard.
3. Where is the money coming from?
If the money came from your overseas salary, moving it into Pakistan through a Roshan Digital Account creates a clean record from day one. If the money is already sitting in a Pakistani account, the paper trail matters even more because when you eventually sell, you will have to prove where it came from.
Clean trail now, clean sale later. There is no shortcut here.

Step 1 — Get Your Identity Documents Right
To buy property in Pakistan while living abroad, you need either a NICOP (National Identity Card for Overseas Pakistanis) or a POC (Pakistan Origin Card). Your CNIC on its own, if that is all you have, will not satisfy the land registry or the Roshan Digital Account application.
Apply through the Pakistani mission in your country or through the Nadra Pak-Identity portal. Processing is usually two to six weeks depending on the mission. Start this first because every other step depends on it.
The 183-day rule, in plain terms
Pakistan’s tax authority (FBR) treats you as a non-resident if you were in Pakistan for fewer than 183 days during the tax year. Non-resident Pakistanis who hold NICOP or POC are entitled to the filer tax rate on property transactions, which is roughly five to seven times lower than the non-filer rate.
That status is not automatic. You apply for it through FBR’s IRIS portal, upload proof of overseas residence, and wait for the Commissioner Inland Revenue to approve it. It must be done before or during the property transfer, not after. Missing this one filing is the single most common way overseas buyers lose money unnecessarily.
Step 2 — Open a Roshan Digital Account
The Roshan Digital Account (RDA) is Pakistan’s dedicated banking channel for overseas Pakistanis. Opening it takes seven to ten days, happens entirely online from your current country, and does not require you to visit Pakistan or any consulate.
Pakistani banks that offer the RDA to overseas Pakistanis currently include HBL, UBL, MCB, Bank Alfalah, Faysal Bank, Allied Bank, Meezan Bank, and Habib Metropolitan (bank availability varies by country of residence). Each bank’s application is a short online form, a video verification call, and uploads of your NICOP or POC plus proof of overseas residence.
Why the RDA matters, even if it feels like extra paperwork
Because the exit, not the entry, is where the RDA earns its place. Pakistan’s State Bank allows you to send money back out of a property purchase funded through an RDA, including rental income during the hold and sale proceeds at the end at any time without requiring prior SBP or bank approval.
If you buy with money that did not come through an RDA, you can still repatriate funds. But the paperwork, the approvals, and the risk of delay are all higher. Spend seven days setting up the RDA now, save three months of approvals later.
| Roshan Apna Ghar: a product under the RDA umbrella that lets you buy outright from your own RDA funds, or finance under-construction and ready property over 3 to 25 years at RDA-eligible profit rates. Not every project qualifies for the financing version; many Invenza-represented projects do. |
| Not sure which of the three goals fits you? Tell us the two things that decide it, roughly what you want to invest, and whether you need monthly income or growth in five years. We will come back with the two or three units across our projects that actually match, and the ones we would rule out for you. No form, no email list. It comes back on WhatsApp. WhatsApp Ahmad Yousaf, CEO — +92 313 0001189 |
Step 3 — Send the Money the Right Way
Transfer from your overseas salary account into your Roshan Digital Account in Pakistan. Use the bank’s own portal, not a third-party service. The transfer takes one to three working days and arrives in your RDA as either PKR, USD, GBP, EUR, or AED depending on which currency sub-account you opened.
From the RDA, you pay the developer or seller directly. The receipt from that transfer is your proof of payment. Keep it. It is also the document that unlocks repatriation when you sell.
What a clean paper trail looks like
Every rupee the developer receives from you should be traceable from your overseas salary deposit → RDA inward remittance → RDA outward payment to the developer’s account. No cash. No off-the-books transfers. No “my cousin will pay the booking fee and I will send him money later” arrangements.
A clean trail costs you nothing. A broken trail can cost you the ability to send sale proceeds back out at all.
Step 4 — Decide Who Signs for You
Unless you plan to fly to Pakistan for every signature, every mutation, and every registry visit, you need a Power of Attorney (POA). This is the legal document that lets someone sign on your behalf.
Special, not general
Grant a special POA that names the exact property, the exact purpose (buying, registering, taking possession) and the exact timeline. Not a general POA that gives one person unrestricted authority over all your affairs in Pakistan. A general POA sounds convenient and ends relationships. A special POA sounds restrictive and keeps your money safe.
The two routes to getting one
Route 1 — the old consulate day. Visit the Pakistani consulate or mission in your country, present your POA document, get it attested, then courier it to Pakistan. Costs a day of your time, works, and has not changed in decades.
Route 2 — NADRA Digital Power of Attorney. Since December 2023, NADRA runs an online POA service at poa.nadra.gov.pk. You submit the signed document online, book a biometric appointment at the nearest Pakistani mission (four fingers from the executor plus two witnesses), pay by card, and nominate the mission that verifies you. Turnaround is 7-21 days post-biometrics depending on the mission.
The attestation window
A consulate-attested POA is typically treated as valid for six months by Pakistani sub-registrars, though we strongly recommend confirming the current window with your Pakistani mission before you rely on it. If possession is more than six months away, time your POA so it covers the registration event.
Three safeguards worth the trouble
- Appoint two attorneys who must act jointly. Each signature requires both.
- Specify the property address, the plot number if available, and the exact scope (“to sign for registration and possession, nothing else”).
- Add a time limit. “This POA is valid until 31 December 2027.” Open-ended POAs outlive relationships.
Step 5 — Buying Without Visiting
Most of our overseas buyers never see the property before they book. That is not a problem if you insist on a few things before any money moves.
What to insist on before you pay
- A video walkthrough of the actual unit or plot (not a developer brochure video) time-stamped within the last 14 days.
- Written confirmation of the exact unit number, floor, orientation, and square footage, on the developer’s letterhead or payment plan.
- A copy of the master NOC or approval letter from the development authority (LDA, CDA, RDA, or TMA as applicable).
- The payment schedule in writing with every one-time fee named; booking, confirmation, utilities, transfer, service charges, TMA, surcharges. Not “additional charges apply.”
- The developer’s cancellation policy. Not every project refunds in full in the first 30 days; some do not refund at all.
What Invenza does for buyers who cannot travel
We send a verified video walkthrough of the actual unit from the site before any payment is made. We hold the developer to a written payment plan with every fee named no “miscellaneous charges” discovered at registration. We attend registration on your behalf (if your POA permits) and send you the stamped documents by courier. The first consultation is 15 minutes on WhatsApp and costs you nothing because our commission is paid by the developer, not by you.
Step 6 — Tax, Briefly
Tax rates for property transactions in Pakistan changed with the Finance Act 2026 and will change again. Any specific percentage quoted in a blog post today may be wrong by the time you read it. For current rates and the filer-versus-non-filer breakdown, read our dedicated guide: Property Tax in Pakistan — Filer vs Non-Filer (2026).
What you need to know in principle: as a non-resident Pakistani with filer status, your tax burden on property purchase and sale is a fraction of what a non-filer or a late-registering buyer pays. The difference is usually between 1 and 3 percent at the filer rate and 10 to 18 percent at the non-filer rate, a gap large enough to change whether an investment is profitable at all.
Register as a non-resident filer with FBR’s IRIS portal before your purchase, not after. The approval must come through the Commissioner Inland Revenue’s inbox before transfer for the filer rate to apply to your transaction.
Which Country Are You Buying From?
The six-step process above is the same for every overseas Pakistani. What differs is the local layer — which banks offer the Roshan Digital Account from your country, which Pakistani mission handles your biometrics, how your home-country tax authority treats Pakistani rental income, and which Invenza projects fit your profile best. Jump to your country below.
| Country | What is included | Jump to |
| United Arab Emirates | Dedicated full guide — AED-to-PKR mechanics, Dubai/Abu Dhabi mission addresses, Dubai Pakistani community anchors, three project picks | Read the UAE guide (full post — publishing November 2026) |
| United Kingdom | Dedicated full guide — HMRC overseas-income reporting, London/Birmingham/Manchester mission list, GBP mechanics, three project picks | Read the UK guide (full post — publishing November 2026) |
| Saudi Arabia | Zakat implications, Pakistani missions in Riyadh and Jeddah, SAR mechanics, three project picks | Scroll down to the Saudi Arabia section |
| Qatar | Doha mission detail, QAR mechanics, three project picks | Scroll down to the Qatar section |
| United States | IRS Form 8938 and FBAR reporting, embassy and consulate network, USD mechanics, three project picks | Scroll down to the USA section |
1. Buying From Saudi Arabia
Saudi-based Pakistanis are the largest overseas Pakistani community by population, roughly 2.6 million people. The buyer profile here skews toward high-value Gulf salaries, retirement planning, and a strong preference for Shariah-compliant financing. Zakat implications and Islamic-finance product preferences shape the decision.
What differs from the six-step process above
Banks offering the RDA from Saudi Arabia: HBL, UBL, MCB, Faysal, Allied, Bank Alfalah and Meezan Bank, Meezan being the Shariah-compliant option many Saudi-based Pakistanis prefer.
Power of Attorney biometrics are handled at the Pakistani Embassy in Riyadh or the Consulate General in Jeddah. Turnaround runs 7-14 days post-biometric appointment.
Zakat: Pakistani property held by a Saudi-resident Pakistani is subject to annual Zakat obligations under some Hanafi and Hanbali rulings. The Zakat basis is usually the current market value for investment property held with intent to sell, or the net rental income for income-producing property. This is a theological and tax question, consult a Shariah-qualified advisor in Saudi Arabia before committing to a specific position. Saudi’s formal Zakat body (ZATCA) does not currently assess Zakat on foreign-held property owned by Saudi residents, but your personal religious obligation is separate.
Three Invenza projects that fit Saudi buyers best
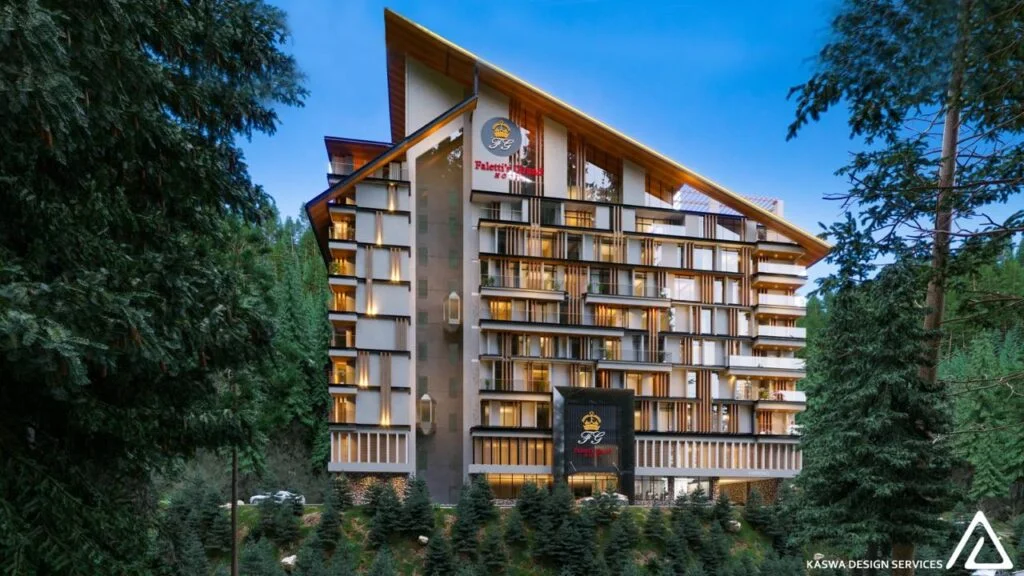
- City Scape Heights Faletti’s Service Apartments — a serviced-apartment hotel-hybrid that works well with Islamic-finance structures through Roshan Apna Ghar.
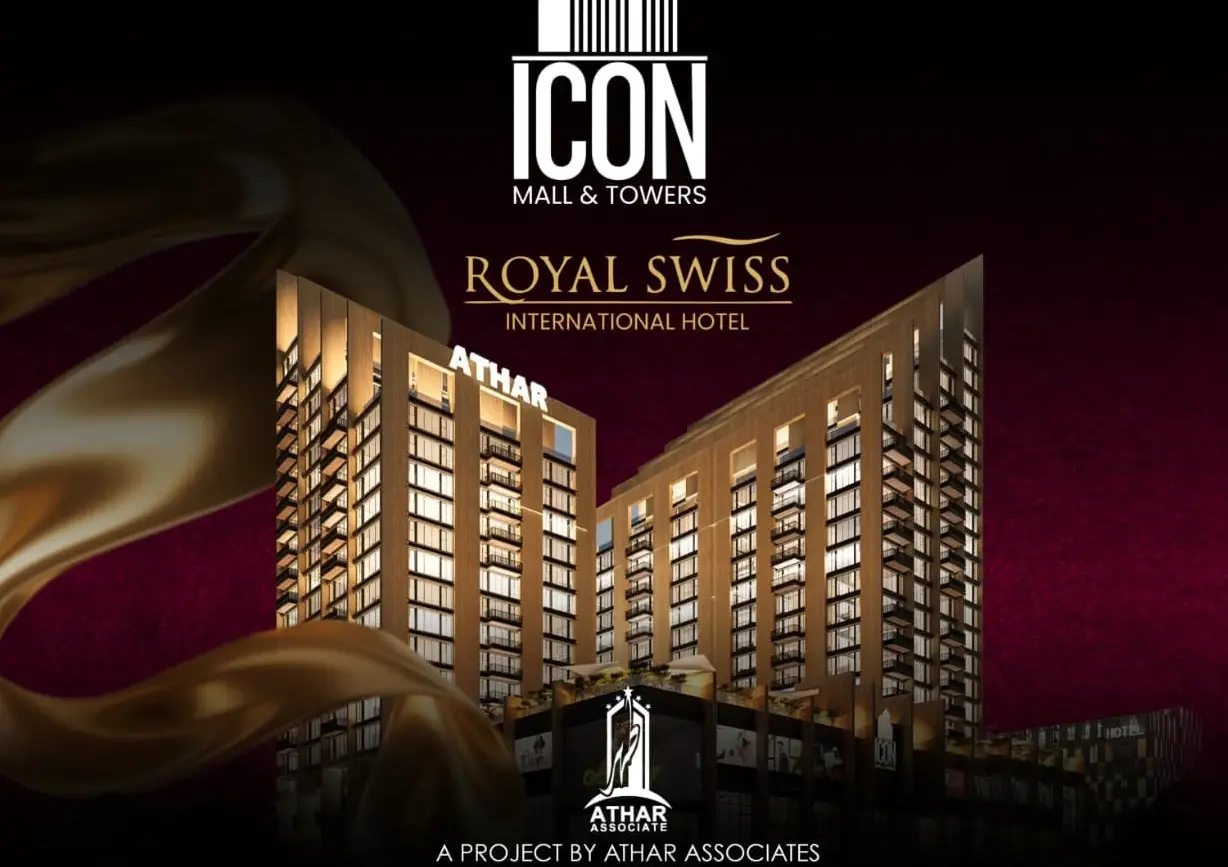
- Royal Swiss International Hotel at Icon Mall & Towers Bahria Town — a managed hotel suite with monthly operator rent; hands-off income for a Saudi-based owner.
- Icon Mall & Towers commercial shops — long-term rental income aligned with retirement cash-flow planning.
2. Buying From Qatar
Qatar’s Pakistani community is smaller, around 200,000 people but per-capita income is among the highest of any Pakistani diaspora. Qatar imposes no personal income tax, which means your Doha salary and your Pakistani rental income are both yours gross.
What differs from the six-step process above
Banks offering the RDA from Qatar: HBL, UBL, MCB, and Bank Alfalah. Fewer options than UAE or Saudi, but all four have mature Qatar branches that handle video KYC for RDA applications.
Power of Attorney biometrics are handled at the Pakistani Embassy in Doha. Qatar’s single mission means no choice of appointment location, book early during busy months.
Zero local income tax means Qatar-based buyers have higher effective yields on Pakistani property than UK or US buyers at the same gross figures. Factor this into any comparison with other investment options you may be considering in Qatar itself.
Flight time from Doha to Lahore is about 4 hours; a return economy ticket in non-peak season runs QAR 1,800-2,800. If you want to visit the property before committing, it is a long weekend, not a full trip.
Three Invenza projects that fit Qatar buyers best
- Signature Rotana Islamabad — Rotana is a brand Qatar-based buyers know from Doha’s own hotel market, which shortens the trust decision.
- The Cube at Faletti’s Etihad Town Lahore — compact ticket size that fits Qatar’s typical first-time overseas investor.
- Mayfair Residencia Canal Road Lahore — the Canal Road location is where many Doha-based Pakistani families retire back to.
3. Buying From the USA
The US-based Pakistani community is around 550,000 people. The typical US buyer is researching for longer, buying with larger ticket sizes, and dealing with the most complex home-country reporting obligations of any diaspora we work with.
What differs from the six-step process above
Banks offering the RDA from the US: HBL, UBL, MCB, and Bank Alfalah. Account opening often requires a video KYC call to confirm identity. Expect the account-opening timeline to run slightly longer than the UAE or UK equivalent, plan for 10 to 14 days rather than 7 to 10.
Power of Attorney biometrics are handled at the Pakistani Embassy in Washington DC or the Consulates General in New York, Los Angeles, Houston, or Chicago. Choose the mission with the shortest wait time, not necessarily the closest geographically, our last few buyers found Houston faster than New York.
The US reporting obligations most overseas Pakistanis miss
As a US tax resident, your global income is taxed by the IRS whether or not it is remitted into the US. If your Pakistani property generates rental income, that income is reportable on your US tax return. Pakistan-US has no tax treaty to prevent double taxation on this income, you can usually claim a foreign tax credit for the Pakistani tax paid, but the paperwork is real.
Two specific reporting forms catch out most US-based Pakistanis:
- Form 8938 (FATCA) — required if your combined specified foreign financial assets exceed USD 50,000 at year-end or USD 75,000 at any point in the year (single filer; thresholds double for joint). A Pakistani RDA counts toward this threshold.
- FBAR / FinCEN Form 114 — required if the aggregate balance of all your foreign bank accounts exceeded USD 10,000 at any single moment during the year. Even a brief spike during a property-booking inward remittance triggers the obligation.
Neither of these forms is complicated to file, but missing them is expensive. Penalties start at USD 10,000 per unreported account and escalate quickly. Talk to a US accountant familiar with Pakistani filings before you move serious money, not after.
Three Invenza projects that fit US buyers best
- City Scape Heights Faletti’s Service Apartments — the serviced-apartment model is one US investors already understand from Airbnb economics.
- Faletti’s Grand Hotel Ayubia — the vacation-asset angle lets US buyers combine personal use with rental yield; the Northern-areas emotional pull is strong for second-generation US Pakistanis.
- Royal Swiss International Hotel at Icon Mall & Towers Bahria Town, hotel-REIT-adjacent income stream familiar to US buyers from their domestic REIT exposure.

Getting Your Money Out When You Sell
This is the question nobody answers well — and the one that stops many overseas Pakistanis from buying in the first place. Here is the short version.
The short version
If you bought through a Roshan Digital Account: the State Bank of Pakistan allows you to send sale proceeds back out of Pakistan at any time, without prior approval. Rental income during the hold period follows the same rule any time, no approval required.
Capital gains are the only piece with a wait. If you sell the property within three years of the original purchase date, the principal repatriates immediately but the capital gain requires a three-year hold from the investment date before it can be repatriated. If you hold for three years or more, the whole amount, principal plus gain is repatriable at once.
If you did not use a Roshan Digital Account
Repatriation is still possible but goes through the ordinary SBP approval route, which is case-by-case and can take months. The paperwork you have to produce is heavier because you need to prove where the original purchase money came from without an RDA transaction history to point to. This is the single biggest practical argument for using the RDA in the first place.
| A dedicated repatriation guide is being published separately in January 2027. It covers the three-year rule in detail, the exact SBP paperwork, and how to time your sale around the rule to maximise what you can send out. Ask us to notify you when it goes live. |
| Ask us the exit question before you ask about the price Tell us when you would realistically want your money back; three years, ten years, never because it is for your children. We will tell you honestly which of our projects fits that and which does not. We would rather lose a booking than sell someone a four-year construction plan when they need liquidity in two. WhatsApp +92 313 0001189 — free consultancy, no obligation |
After Possession: Who Looks After It?
If you buy a property while living abroad, someone has to look after it. There are three honest options.
1. Managed by an operator
For hotel suites, serviced apartments, and some branded residences, the developer or a hotel operator takes the keys and runs it as a business. You receive a monthly or quarterly cheque. You never have to think about tenants, geysers, or missing rent. This is the easiest option and usually the lowest-yielding — the operator takes a cut, typically 40 to 60 percent of gross rental income.
2. Let to a tenant
For apartments and houses, a local letting agent (or your family member) finds a tenant and manages the lease. Gross yields are higher but your net exposure to tenant risk, repair bills, and vacancy is real. Factor 15 to 25 percent off the gross figure before you compare it to the operator-managed option.
3. Left locked
Some overseas buyers simply lock the property, pay the maintenance and service charge, and treat it as a capital-growth asset. This works for plots and some apartments in secure gated communities. It does not work for mall commercial shops, which lose value fast if left unoccupied.
What Overseas Buyers Actually Buy With Us
Across the Invenza portfolio, three broad patterns emerge for overseas buyers. Match yours.
1. If you want monthly income
Managed hotel suites and serviced apartments. Royal Swiss International Hotel at Icon Mall & Towers (Bahria Town, Lahore), The Cube at Faletti’s Etihad Town (Lahore), Faletti’s Grand Hotel Ayubia (Northern Pakistan), Signature Rotana Islamabad (Islamabad), City Scape Heights Faletti’s Service Apartments (Lahore). Monthly operator rent, no tenant management, net yields typically 6 to 10 percent after operator share.
2. If you want capital growth
Pre-launch or early-phase apartments in high-growth areas. Bahria Sky 2 (Bahria Orchard Phase 4, Lahore), Mayfair Residencia (Canal Road, Lahore), Serene Heights (Lahore), Icon Avenue (Lahore). Hold 3 to 5 years through completion for the capital gain.
3. If you want somewhere to live later
Residential plots, villas, or branded residences in gated developments. Bahria Orchard Phase 4 plots, Golden Tulip Islamabad branded residences, Signature Rotana Islamabad branded residences. Capital protection with the option to move in later if you ever return.
A note on prices
Prices for Lahore commercial, residential, and hotel-suite property have moved in a wider range than the headline PKR depreciation suggests, because many developers price in USD-indexed terms for the overseas segment. We quote the current PKR price and the USD equivalent at today’s interbank rate on every project page. Check both before you compare across projects.
Five Mistakes We See Repeatedly
None of these are hypothetical. Each one has cost at least one buyer we spoke to a serious amount of money.
- Skipping the FBR non-resident filer registration. The non-filer tax rate is five to seven times the filer rate. The registration is free. People skip it anyway, usually because nobody told them.
- Paying any amount in cash or through an unnamed intermediary. Breaks the paper trail. Blocks repatriation of the sale proceeds years later. Not worth any discount offered to do it this way.
- Trusting a general Power of Attorney to a relative “just in case.” Once signed, it is hard to narrow. Keep it special, keep it two-attorneys-jointly, keep it time-bound.
- Buying from a Facebook post, a WhatsApp forward, or a cold caller claiming to represent a project. The developer’s own office is the only place that can confirm current availability and real prices. Everyone else layers a markup.
- Ignoring the exit strategy at the time of purchase. The question “how do I get the money back out?” has to have an answer the day you buy, not the day you want to sell. If the answer is not clear, do not buy.
| Get the three documents before you commit anything: For whichever unit you are considering, we will get you the developer’s current payment plan, the project’s approval reference, and a dated allocation availability confirmation in writing, from the developer, not from us. If you are weighing two projects, we will get all three for both so you can compare like with like. Then decide. WhatsApp Ahmad Yousaf, CEO — +92 313 0001189 |
Frequently Asked Questions
Q1: Can I buy property in Pakistan without going there?
A. Yes. Overseas Pakistanis buy property in Pakistan from the UAE, UK, Saudi Arabia, Qatar, USA, Canada and Australia every week without visiting during the purchase. The three practical requirements are: valid NICOP or POC, a Roshan Digital Account, and a Power of Attorney for someone in Pakistan to sign at the registry. Expect six to ten weeks for a resale or ready property, and anywhere from a few days to several months for an under-construction booking depending on the developer.
Q2: Do I need a NICOP or POC to buy property in Pakistan?
A. Yes if you intend to use overseas banking facilities such as the Roshan Digital Account, and effectively yes in practice at most Pakistani property registries. A CNIC alone is accepted for in-person transactions by Pakistani-passport holders physically present, but will not unlock the overseas banking channels that make the entire process workable from abroad.
Q3: What is a Roshan Digital Account and do I really need one?
A. The RDA is Pakistan’s dedicated banking channel for overseas Pakistanis. You open it online from your current country of residence, use it to send money into Pakistan for property purchases, receive rental income into it, and send sale proceeds back out of it. You do not strictly need one to buy property, but you almost certainly need one to send the proceeds back out without months of SBP approvals. Open the RDA before you buy.
Q4: How much tax do overseas Pakistanis pay when buying property?
A. As a non-resident Pakistani with filer status, your tax rate on property purchase is typically a small single-digit percentage of the declared value. As a non-filer, the rate is multiple times higher. Specific percentages change with each Finance Act, our dedicated property tax guide carries the current post-Finance-Act-2026 figures. Register for non-resident filer status with FBR’s IRIS before your purchase, not after.
Q5: Should I give a general or a special Power of Attorney?
A. Always a special POA. Name the specific property, the specific purpose (buying, registering, taking possession), and a specific expiry date. A general POA gives one person unrestricted authority over all your affairs in Pakistan, the convenience is not worth the risk. We recommend appointing two attorneys who must act jointly.
Q6: Can I get a Power of Attorney without visiting the consulate?
A. Partially. NADRA launched its Digital Power of Attorney service at poa.nadra.gov.pk in December 2023. The application is online, but biometric verification is still done in person at the nearest Pakistani mission, a short appointment rather than a full consulate day. Turnaround is 7-21 days post-biometric depending on the mission. The old route (full consulate attestation of a paper POA) remains available where the digital service is slower.
Q7: How do I get my money out of Pakistan when I sell?
A. If you bought through a Roshan Digital Account, the State Bank allows sale proceeds and rental income to be repatriated at any time without prior approval. Capital gains on property sold within three years of the original purchase date require a three-year hold from the investment date before the gain itself can be repatriated — the principal can go out immediately. If you did not use an RDA, repatriation is still possible but goes through the ordinary SBP approval route, which is slower and more paperwork-heavy.
Q8: How long does buying property take from abroad?
A. For a resale or ready property with POA and RDA already in place: six to ten weeks typically. For an under-construction booking: a few days to a few weeks for the booking itself; construction and handover then take the project’s stated timeline (typically 3 to 4 years for high-rise projects). The slowest step is almost always the Power of Attorney cycle, not the money transfer.
Q9: What should I check before paying a single rupee?
A. Written confirmation of the exact unit (number, floor, orientation, square footage) on the developer’s letterhead; a copy of the master NOC or approval letter from the relevant development authority; the complete payment schedule with every one-time fee itemised; the developer’s written cancellation and refund policy; and a time-stamped video walkthrough of the actual unit from within the last 14 days.
Q10: Does Invenza charge overseas buyers a fee?
A. No. Our commission is paid by the developer on completed bookings. The first consultation is 15 minutes on WhatsApp and costs you nothing. You are not expected to compensate us for the research, the walkthroughs, or the paperwork support — all of that is covered by the developer-side commission.
Q11: I live in a country not covered in the sections above. Can you still help?
A. Yes. The six-step process is the same in every country. The only differences are which Pakistani banks offer the RDA in your country, which Pakistani mission handles your biometrics, and your home-country tax treatment of Pakistani rental income. Message us on WhatsApp with your country of residence and we will walk you through the specifics for your situation.
Q12: Can overseas Pakistanis get financing from Pakistani banks to buy property?
A. Yes, through Roshan Apna Ghar. Eligible overseas Pakistanis can finance ready or selected under-construction properties over 3 to 25 years, with the loan serviced from the RDA. Not every project qualifies, many Invenza-represented projects do. Ask us for the current list of financing-eligible projects before you start the application.
Talk to Invenza Group
If you are abroad and thinking about buying property in Pakistan, the first conversation costs you nothing and takes 15 minutes on WhatsApp.
We will ask what the property is for, where you are based, what budget you have in mind, and what your timeline is. Based on your answers, we will send you two or three project shortlists with real numbers, payment plan, projected yield or capital growth, delivery date, honest risk assessment. No pressure, no “limited units left” messaging, no cold calls afterwards.
Message Ahmad Yousaf on WhatsApp (CEO, Invenza Group Pvt. Ltd.) or visit our office in Bahria Orchard, Lahore. If you are reading this from the UAE, UK, Saudi Arabia, Qatar or the USA, mention your city in the first message so we can route you to the overseas desk.
| Important: This article is general guidance for overseas Pakistanis, not tax or legal advice. Tax rates, State Bank rules and attestation requirements change, and your own position depends on facts specific to you. Confirm anything that affects a decision with FBR, your bank, or a qualified lawyer or tax adviser before you transact. Invenza Group is a property consultancy, not a law firm or a tax practice. |
